
The structure with the most favourable headline tax treatment may not be the right fit for a high-net-worth investor. For tax efficient investment structures for HNWIs Luxembourg, the outcome depends on more than a vehicle’s tax profile: ownership, asset type, substance and cross-border obligations all matter.
It is understandable to compare holding companies with regulated or alternative fund structures by their apparent tax advantages. Yet each serves different investment and governance needs, and the same structure can produce different results depending on an investor’s circumstances. This guide explains the main Luxembourg options, how their functions and tax treatment differ, and how to assess them against cross-border investment objectives.
We’ll consider the practical factors that shape suitability, including flexibility, governance, substance and ongoing administration. We’ll also identify issues that require case-specific legal and tax analysis before a decision is made. For investors managing diversified, long-term portfolios, a consistent framework can make these considerations clearer without treating any structure as a universal solution.
Key Takeaways
- Assess tax efficiency through the full picture: investment purpose, ownership, cash flows and applicable obligations, rather than a structure’s headline tax profile alone.
- Compare Luxembourg holding-company and fund routes by their intended purpose, ownership arrangements, governance and investment activity.
- Use investor residence, asset mix, co-investors and exit plans to evaluate tax efficient investment structures for HNWIs Luxembourg.
- Separate company-level tax considerations from investor-level treatment, including the potential implications of distributions and realised gains.
- Map objectives and ownership before reviewing legal, tax and operational requirements, then assess whether the structure supports long-term portfolio plans.
Tax-efficient investment structures for HNWIs in Luxembourg: what efficiency really means
For high-net-worth investors, tax efficiency is not a property of a company name or fund label. It means lawfully aligning an investment’s purpose, ownership, cash flows, and applicable tax and compliance obligations. Assess a structure in the context of the investor and the assets it holds, not by a headline rate alone.
In practical terms, a holding vehicle owns and manages investments on behalf of its owners, while an investment fund pools or organises capital under a defined investment framework. The appropriate form depends on factors such as who owns the assets, how investment decisions are made and how returns are distributed. Neither form produces an identical tax result for every investor or asset.
What does tax efficiency mean for a high-net-worth investor?
A sound assessment separates the vehicle’s tax treatment from the investor’s personal tax position. It also accounts for the full lifecycle: formation, governance, reporting, ongoing administration, distributions and exit. Tax efficiency is distinct from secrecy, tax avoidance or a guaranteed reduction in tax. The key question is whether the arrangement has a genuine investment rationale and meets the obligations that apply to it.
Consider an investor resident outside Luxembourg who is weighing a direct investment against investing through a Luxembourg entity. The entity’s treatment is only one part of the analysis. The investor’s residence, the source and character of income, any applicable treaty provisions and anti-abuse rules could also affect the result. This example illustrates questions to investigate; it does not predict tax treatment.
Why Luxembourg is considered for cross-border investment structures
Luxembourg is an established financial centre used in cross-border investment planning. Its role in a structure needs to be considered alongside the jurisdictions where investors reside, assets are located and income arises. Holding an investment through a company and pooling capital through a fund are distinct approaches, with different ownership, governance and operational considerations.
Fund structures also vary in their legal and regulatory features. For example, the Specialized Investment Fund (SIF) is one Luxembourg fund category; its suitability depends on the fund’s purpose and the investors’ circumstances. A structure overview can help clarify these distinctions, including the Luxembourg investment structures overview.
For tax efficient investment structures for HNWIs Luxembourg, evaluate purpose, ownership, cash flows and obligations together. This gives investors a more useful starting point than assuming Luxembourg incorporation alone determines the outcome.
Luxembourg holding and fund structures: understand the main options
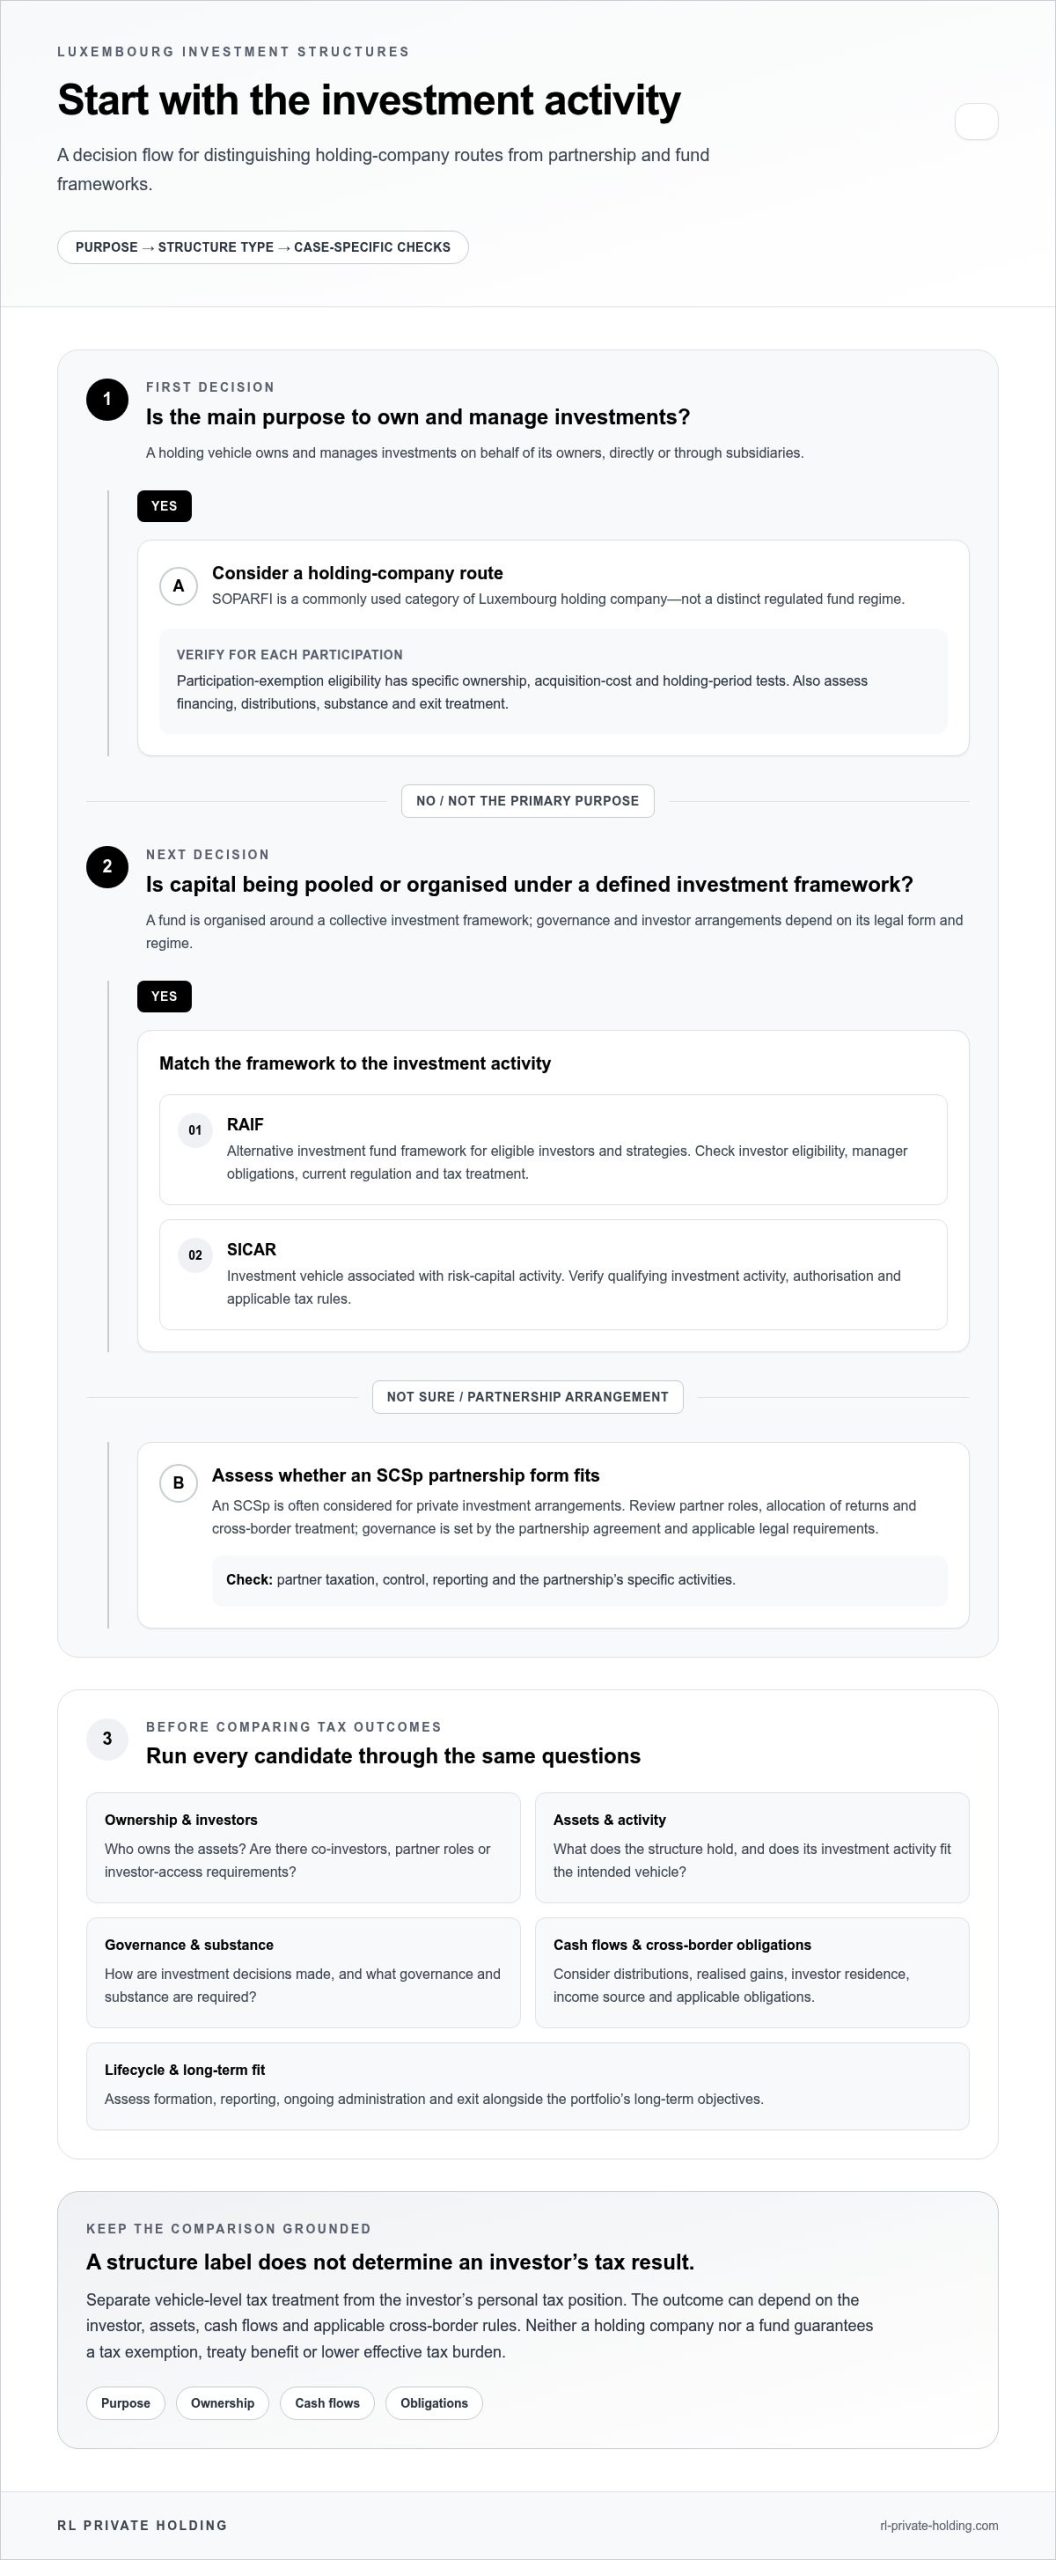
Choosing between a holding company and a fund starts with the intended investment activity. A holding company generally owns investments directly or through subsidiaries. A fund is designed around a collective investment framework, with governance and investor arrangements shaped by its legal form and regime. Neither category guarantees a tax exemption, treaty benefit or lower effective tax burden.
SOPARFI is a commonly used category of Luxembourg holding company, rather than a distinct regulated fund regime. Its treatment depends on the company’s facts and whether relevant conditions are met. For example, the participation exemption has specific ownership, acquisition-cost and holding-period tests, and eligibility should be assessed for each participation. Luxembourg’s tax framework provides broader jurisdictional context, but a general overview cannot determine the result for a particular investor.
| Structure | Typical purpose | Investor considerations | Governance | Points to verify |
|---|---|---|---|---|
| SOPARFI | Holding shareholdings and organising investment ownership. | Suitable where direct ownership through a company fits the portfolio and ownership plan. | Corporate governance follows the chosen legal form and company arrangements. | Participation conditions, financing, distributions, substance and exit treatment. |
| SCSp | Partnership form often considered for private investment arrangements. | Review partner roles, allocation of returns and cross-border treatment. | Set by the partnership agreement and applicable legal requirements. | Partner taxation, control, reporting and the partnership’s specific activities. |
| RAIF | Alternative investment fund framework for eligible investors and strategies. | Investor access and fund-level requirements affect suitability. | Fund governance and relevant alternative-investment-fund rules apply. | Eligibility, manager obligations, current regulation and tax treatment. |
| SICAR | Investment vehicle associated with risk-capital activity. | Its investment scope may not suit a diversified holding portfolio. | Depends on the vehicle’s form and regulatory status. | Qualifying investment activity, authorisation and applicable tax rules. |
| SPF | Private wealth management company for qualifying family wealth activities. | Its permitted purpose may limit its fit for broader commercial investment activity. | Corporate governance applies, subject to the SPF’s specific framework. | Eligible investors, permitted activities and subscription-tax obligations. |
When might a holding-company route be considered?
A holding structure may organise shareholdings, financing and ownership across a portfolio. Before selecting it, map how capital enters the company, how income may be distributed and how a potential disposal could be treated. These questions depend on the assets, investor residence and applicable rules, so assess the structure as part of the wider investment plan.
When might an investment fund structure be considered?
A fund may be relevant when pooled investment governance and defined investor arrangements are central. A holding vehicle, by contrast, may suit direct ownership by a company. Fund-regime eligibility, investor access and regulatory status require case-specific review. For further context on partnership design, see the SCSp strategic guide.
Comparing tax efficient investment structures for HNWIs Luxembourg means examining purpose, ownership, governance and obligations together. Investors aligning vehicle choice with long-term portfolio management can also explore RL Private Holding’s investment perspective.
How to compare Luxembourg structures for tax and investment fit
A useful comparison starts with the investor and the portfolio, not with a preferred vehicle. The same structure may suit one ownership chain and be impractical for another. Use a decision matrix to record the facts that can change the analysis, then review corporate and investor-level tax questions separately.
| Decision factor | Questions to map | Why it matters |
|---|---|---|
| Investor and residence | Where are the investor and other owners tax resident? What type of investor is involved? | Residence and investor status can affect how income, distributions and gains are treated. |
| Assets and ownership | What assets are held, and through which entities or jurisdictions? | A single direct investment may call for a different analysis from a portfolio spanning companies, property or fund interests. |
| Co-investors and governance | Are there other investors? Who makes decisions, and how are rights and responsibilities documented? | Shared ownership may call for defined governance and reporting arrangements. |
| Cash flows and exit | Will income be reinvested or distributed? Is financing expected, and how might an exit occur? | The timing and character of cash flows can affect both entity-level and investor-level analysis. |
Which investor and portfolio factors can change the analysis?
Map the ownership chain across relevant jurisdictions, alongside expected income, financing, reinvestment, distributions and possible exits. Assess the full portfolio rather than one asset in isolation. For example, a structure chosen for a long-term shareholding may have different governance and cash-flow implications if it also holds property or accommodates co-investors.
Direct investment and pooled activity also need separate consideration. Direct ownership focuses on the relationship between an investor, a vehicle and its assets. A pooled arrangement adds collective governance, investor rights and fund-level administration. These differences affect operational fit as well as tax questions.
How do governance, substance, and cross-border rules affect fit?
Decision-making, documentation and operational substance should align with the vehicle’s stated purpose and actual activity. Consider who exercises control, where key decisions are made, what records support those decisions and how the structure will meet its reporting responsibilities. Governance is part of the tax analysis because it helps establish how the arrangement operates in practice.
Before implementation, review the current application of treaty provisions, anti-abuse rules, transfer-pricing requirements and interest limitations across the relevant jurisdictions. Applicable EU and Luxembourg rules can depend on the structure and circumstances, so conclusions require case-specific review. Where family-office governance is central, include the family-office investment strategy in the broader assessment.
This disciplined comparison helps assess tax efficient investment structures for HNWIs Luxembourg against investment objectives and practical obligations, rather than relying on headline tax treatment alone.
Tax and compliance due diligence before choosing a Luxembourg structure
Select a structure only after assessing its investment purpose, ownership and obligations together. A tax profile that appears favourable in isolation may not reflect the investor’s residence, the assets involved or the rules of other relevant jurisdictions. Document the review before formation or implementation, and revisit it when ownership, activities or applicable rules change.
Tax treatment depends on the facts and the law applicable to each investor, entity, asset and transaction.
What information should be mapped before implementation?
Start with a clear record of who owns and controls the proposed structure, where each investor is tax resident, and which assets and jurisdictions are involved. Then document the intended investment horizon, financing arrangements, co-investment terms, cash-flow assumptions and potential exit routes. This gives legal and tax analysis a practical basis rather than leaving it to rely on a structure diagram alone.
- Define the objectives. Record the investment purpose, portfolio role and expected holding period.
- Map ownership and assets. Identify investors, beneficial owners, entities, asset locations and relevant jurisdictions.
- Model expected activity. Set out income sources, financing, reinvestment, distributions and possible disposals.
- Assign governance responsibilities. Document decision-making roles, operational responsibilities and the records needed to support them.
- Obtain current legal and tax review. Test the proposed structure against investor-specific facts and rules in each relevant jurisdiction before implementation.
Which Luxembourg and cross-border issues require current review?
Review the potential treatment of corporate income, withholding tax, realised gains and participation-related regimes against the structure’s actual circumstances. Confirm applicable conditions rather than assuming an exemption or treaty benefit. The review should also address reporting duties, anti-abuse provisions, substance, transfer pricing and interest limitations where relevant. Fund structures may raise additional questions about investor eligibility, regulatory status and ongoing fund obligations.
Recordkeeping and administration are part of the assessment, not matters to defer until after formation. Consider how the entity will document decisions and transactions, meet filing and reporting responsibilities, and maintain governance that reflects its activities. The required arrangements depend on the structure and applicable law.
Pillar Two should also be considered carefully. Its relevance depends on whether the relevant group and entities fall within the rules’ scope; it should not be assumed to apply to every HNWI or investment vehicle. Confirm the current position for the specific group and reporting period rather than relying on a general description.
This due-diligence sequence helps investors assess tax efficient investment structures for HNWIs Luxembourg on a current, evidence-based footing. To connect structure considerations with long-term investment objectives, explore RL Private Holding’s investment management perspective.
Building a Luxembourg investment structure around long-term portfolio objectives
A Luxembourg structure should support the investment strategy throughout its lifecycle, from initial ownership and capital deployment to ongoing oversight, distributions and exit. Tax considerations belong in that assessment, but they cannot replace sound investment management. The structure also needs to reflect who owns the assets, who makes decisions and how long the portfolio is expected to hold them.
How should the structure support investment activity over time?
Plan beyond the initial investment. A private equity position may involve follow-on funding, active portfolio oversight and an eventual disposal. Venture capital investments, including those in technology businesses, may call for staged capital deployment and clear records of investment decisions. Real estate assets can involve continuing management and income flows that differ from those of a company holding. Each activity can affect how ownership, governance and reporting should be organised.
Consider these elements together:
- Investment and follow-on capacity: Determine how additional capital may be deployed and who approves each commitment.
- Portfolio oversight: Set clear responsibilities for monitoring investments and maintaining decision records.
- Cash-flow planning: Consider whether income is expected to be reinvested or distributed, and how that aligns with the owners’ objectives.
- Exit planning: Include potential timing and routes to disposal in the ownership and governance analysis.
Review the arrangement as the portfolio changes. New co-investors, different asset classes, revised holding periods or changes in ownership objectives may affect whether the structure remains suitable. A framework designed for one investment should not automatically be assumed to fit a broader portfolio.
How RL Private Holding approaches investment management
RL Private Holding is headquartered in Luxembourg and operates with a global portfolio spanning technology, real estate, asset management, private equity and venture capital. Its activities include venture capital funding, private equity investment management, real estate asset management and wealth management services. This range underscores why investment structures should be considered alongside portfolio strategy, governance and the distinct characteristics of each asset class.
For investors considering tax efficient investment structures for HNWIs Luxembourg, the objective is a coherent arrangement that can support ownership and investment decisions over time. Tax analysis informs that work, but no structure guarantees a particular tax result.
To learn more about the firm’s investment activities, explore RL Private Holding.
Build a structure that supports your investment objectives
The most appropriate structure is not necessarily the one with the most favourable headline tax treatment. It is the one whose purpose, ownership, governance and cash flows fit the portfolio and the investors behind it. Holding companies and fund structures serve different functions, and their treatment depends on the relevant facts and applicable law.
A disciplined assessment separates entity-level questions from each investor’s personal tax position, while accounting for reporting, administration and the intended investment horizon. For tax efficient investment structures for HNWIs Luxembourg, current legal and tax review is essential before selecting or implementing an arrangement.
That perspective also reflects how RL Private Holding approaches investment activity. Luxembourg-headquartered, the firm manages a global portfolio across technology, real estate, private equity and venture capital. These different areas require investment decisions to align with the assets, ownership arrangements and long-term objectives involved.
Explore RL Private Holding’s investment management activities to learn more about its portfolio focus. A well-considered structure can provide a sound framework for pursuing investment objectives with clarity and discipline.
Frequently Asked Questions
Is Luxembourg a tax-efficient jurisdiction for HNWIs?
Luxembourg may be suitable for some cross-border investment arrangements, but it is not automatically tax-efficient for every investor. The outcome depends on the investor’s tax residence, assets, ownership chain, cash flows and the laws of relevant jurisdictions. Treaties, anti-abuse rules, reporting duties and ongoing administrative requirements can also affect the analysis. Compare structures against the investment purpose and full lifecycle, rather than assuming a Luxembourg vehicle will reduce tax.
What is the difference between a SOPARFI and a Luxembourg investment fund?
A SOPARFI is a holding-company category used to own and manage investments, while an investment fund is organised around an investment framework and may pool capital from investors. They differ in purpose, ownership, governance and applicable regulatory considerations. A SOPARFI is not, by itself, a special tax exemption. A fund’s treatment depends on its particular regime and circumstances. Make the comparison based on who invests, what assets are held and how decisions are made.
Can a Luxembourg holding company reduce tax on investment income?
It may qualify for particular tax treatment in some circumstances, but incorporation alone does not ensure a reduction. For example, participation-related exemptions have eligibility conditions that depend on the investment and the company’s facts. The analysis should cover income at the company level and the investor’s treatment when income is distributed or gains are realised. Residence, source-country rules, substance and anti-abuse provisions may also affect the result.
How do SCSp, RAIF, SICAR, and SPF structures differ?
These structures serve different purposes. An SCSp is a partnership form often considered for private investment arrangements. A RAIF is an alternative investment fund framework, while a SICAR is associated with risk-capital investment. An SPF is intended for qualifying private wealth management activities and has a more restricted purpose. Their investor access, governance, regulatory position and tax treatment are not interchangeable, so suitability requires review of the intended activity and current rules.
What substance requirements may apply to a Luxembourg holding structure?
Substance expectations depend on the structure, its activities, applicable tax rules and any relevant treaty or anti-abuse analysis. Review where decisions are genuinely made, who performs governance functions, what documentation supports those decisions and whether the company’s operations align with its stated role. A registered presence alone may not address every relevant issue. Assess substance alongside ownership, financing, reporting and the jurisdictions in which the company and investors operate.
Does a Luxembourg investment structure change an investor’s personal tax obligations?
A Luxembourg structure does not automatically replace or remove an investor’s personal tax obligations. The investor’s residence jurisdiction may tax distributions, gains or other income under its own rules, and source-country obligations may also be relevant. Assess the vehicle’s tax treatment and each investor’s position separately. Before investing or receiving proceeds, consider the character and timing of cash flows across all relevant jurisdictions.
What should HNWIs review before setting up a Luxembourg investment structure?
Begin by documenting investor residences, beneficial ownership, assets, relevant jurisdictions and the structure’s intended purpose. Map expected financing, income, reinvestment, distributions and exit plans, then assess governance, substance, reporting and administration. Obtain current Luxembourg and cross-border legal and tax analysis before implementation, including review of applicable corporate, withholding and capital-gains rules. The primary keyword, tax efficient investment structures for HNWIs Luxembourg, describes a planning question, not a guaranteed tax outcome.